By Chance, owner of Southern Gutters FL · Published · Last updated
Key takeaways
- Gutters are typically treated as part of the dwelling, so sudden wind damage is often a covered type of loss.
- Wear, rust, rot and neglect are commonly excluded, so cause matters as much as damage.
- Florida hurricane deductibles are often a percentage of the dwelling limit, which can exceed a gutter-only repair.
- Gutter damage is usually most relevant as part of a larger claim that includes roof, fascia or soffit.
- Your insurer decides coverage; read your declarations page and ask your agent.
Often, when hurricane winds damage gutters that were in sound condition. Most Florida homeowners policies treat gutters as part of the dwelling and cover sudden wind damage, while wear, rot and neglect are commonly excluded. A percentage-based hurricane deductible can still exceed a gutter-only repair, and only your insurer decides coverage on your claim.
After every storm season, homeowners ask us some version of the same question: does insurance cover gutter damage in Florida? The honest answer is that it depends on your policy, the cause of the damage and the size of your deductible, and only your insurer can decide coverage on your claim.
What we can do is explain, in general terms, how Florida homeowners policies commonly treat gutters, why the hurricane deductible changes the math so much, and what documentation helps whichever way you go. We are a gutter company, not an insurance agent, adjuster or attorney, so treat this as background reading before you talk to the people who can give you a real answer.
Homeowners insurance and gutters: how policies usually see them
Most Florida homeowners policies cover the house itself under the dwelling portion of the policy, and gutters, downspouts, fascia and soffit are generally considered part of that structure. Wind is commonly a covered peril, so a gutter torn off by hurricane-force gusts is the kind of sudden, accidental damage policies are written for.
What policies commonly exclude is damage from wear and tear, gradual deterioration, corrosion, rot and lack of maintenance. A gutter that fell because the fascia behind it had been rotting for years may be viewed very differently from one ripped off a sound board by a storm. Flood damage is excluded from standard homeowners policies and handled by separate flood coverage.
Not legal or insurance advice
Policies differ by company and by endorsement. Your declarations page, your policy wording and your insurer's adjuster decide what is covered. Questions about your rights belong with your agent, the Florida Department of Financial Services consumer helpline or a licensed attorney.
How the hurricane deductible in Florida changes the math
Florida policies usually carry two deductibles: a regular one for most losses, and a separate hurricane deductible. Insurers in Florida are required to offer hurricane deductible options that are commonly expressed as 2, 5 or 10 percent of the dwelling coverage limit, and your declarations page shows the actual amount that applies.
The hurricane deductible generally applies to damage that happens during the period that starts when a hurricane watch or warning is issued for any part of Florida and ends 72 hours after the last one is lifted. It is also designed to apply once per season rather than once per storm, though exactly how a second storm in the same year is handled depends on your policy.
Here is why that matters for gutters. On many homes, a percentage-based hurricane deductible is larger than the cost of replacing a few runs of gutter. If gutters are the only damage, the claim may not pay anything after the deductible. If the same storm also damaged the roof, fascia, soffit or screen enclosure, the gutters become one line item in a larger claim.
Wind damage claim, gutters and common scenarios
| Situation | How it is commonly treated | Question for your insurer |
|---|---|---|
| Gutters torn off by hurricane winds, sound fascia | Often a covered wind loss, subject to the hurricane deductible | Does my damage exceed my hurricane deductible? |
| Gutters and roof edge both damaged in the storm | Often handled together as one wind claim | Should my contractor itemize gutters and fascia separately? |
| Gutter fell due to long-term fascia rot | Commonly excluded as wear or neglect | Is any resulting damage covered? |
| Tree limb from a storm crushed a gutter | Often treated as storm damage to the dwelling | Is debris removal included? |
| Damage from a non-hurricane thunderstorm | Usually the regular deductible, not the hurricane one | Which deductible applies to this date of loss? |
| Water damage from rising floodwater | Excluded from homeowners; flood policy instead | Does my flood policy apply? |
Storm damage documentation that supports a gutter insurance claim
Whatever your coverage turns out to be, good records make every conversation easier. Start before cleanup, and keep everything in one folder on your phone or computer.
- Wide photos of every side of the house, then close-ups of each damaged run, hanger, corner and downspout.
- Photos of exposed or cracked fascia and any interior stains near the damaged area.
- Video walking the perimeter, narrating what you see and the date.
- Any older photos showing the gutters in good shape before the storm, which helps on the wear-and-tear question.
- Receipts for any emergency make-safe work, and the damaged pieces until the adjuster says you can discard them.
- A written, itemized repair estimate from a contractor.
Our hurricane gutter damage repair visits include photos and a written estimate that separates gutters, downspouts, fascia and soffit, which is the format adjusters generally find easiest to review. For the hour-by-hour version of what to do right after a storm, see our guide to the first 48 hours after hurricane gutter damage.
Deadlines, red flags and where a gutter contractor fits
Report promptly
Florida law now sets tighter limits on how long you have to report a property claim. Under the current rules, a new claim generally has to be reported within one year of the date of loss, with a somewhat longer window for supplemental claims. Check your policy and confirm the current deadline with your insurer, and do not wait.
Watch for these
Florida restricts contractors from offering to waive or rebate your deductible or offering gifts for filing a claim. If someone at your door makes that offer, it is a warning sign. A legitimate contractor gives you a written estimate, county license details on request and a certificate of insurance.
What we do and don't do
We inspect, photograph, write the estimate and do the repair. We do not negotiate claims, interpret policies or act as your adjuster. Across Broward County and Miami-Dade County, we are happy to meet an adjuster on site when the schedule allows so they can see the damage with someone who measured it.
Storm damage or old wear? What we see from the ladder
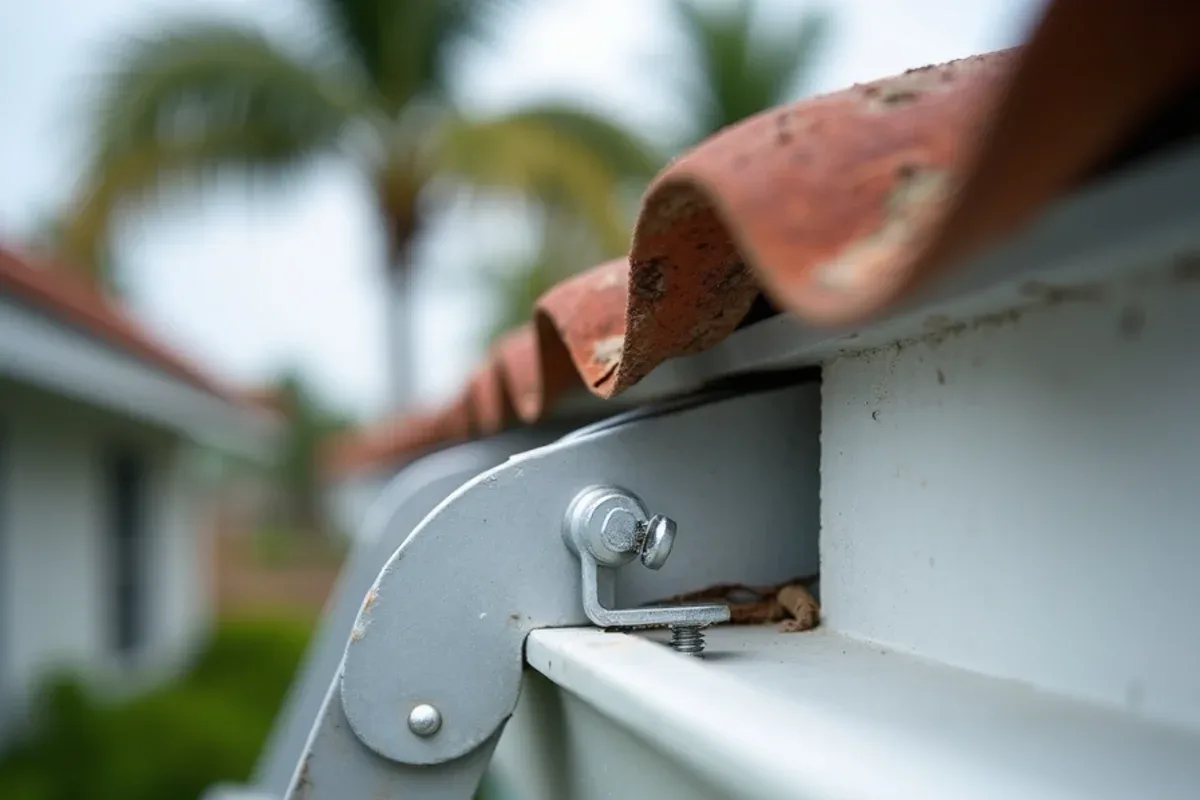
The question adjusters care about most, sudden storm damage versus long-term deterioration, is also the first thing our crew looks at. The evidence is usually there in the metal and the wood, and we photograph it as we find it rather than drawing conclusions for anyone.
| What we find | Points toward | Why it matters |
|---|---|---|
| Hangers torn or bent, screws still in solid fascia | Force from wind or impact | Sound wood with fresh tear marks suggests sudden damage |
| Screws pulled out with soft, crumbly wood | Fascia rot that predates the storm | Rot is commonly treated as wear, even if the storm finished the job |
| Old spike fasteners backed out along the run | Long-term loosening | Shows the attachment had been failing over time |
| Pitting and white corrosion on coastal gutters | Salt-air wear | Corrosion is usually excluded as deterioration |
| Fresh dents, crushed downspouts, limb strikes | Impact from storm debris | Debris marks are often clear in close-ups |
On our estimates, anything that looks like older wear is listed separately from what the storm clearly did, and the fascia, soffit and gutter lines are kept apart too. When the wood behind a torn run is soft, our fascia board repair shows up as its own item, so you and your insurer can see exactly what was storm-related and what was not.
What a clear, itemized gutter estimate lists
- Linear feet of each damaged run, plus gutter size and color
- Downspouts, elbows, outlets, miters and end caps, counted separately
- Fascia and soffit lengths, with notes on any pre-existing rot
- Storm debris removal and haul-away as their own line
- Dated before, during and after photos tied to each line
Debris removal deserves a note of its own. Gutters packed with shredded fronds after a hurricane will overflow in the next storm whether or not any claim is filed, so a post-storm debris clean-out is often worth doing promptly, after photos are taken. Ask your insurer how they treat that cost; we simply make sure it is documented and billed as its own item.
Know your deductible, document everything, then decide
Hurricane gutter damage is often a covered wind loss, but cause, condition and deductible decide whether a claim makes sense. Read your declarations page, photograph everything before cleanup, report promptly, and get an itemized estimate that keeps storm damage separate from older wear. Then let your agent and insurer answer the coverage question.
When you need that estimate, call Southern Gutters FL. Our family-owned crew inspects, photographs and writes up the repair in plain line items, and we accept Visa, Mastercard, American Express and Discover for the work itself.
Questions about does insurance cover gutter damage florida
Is it worth filing a claim just for gutters?
It depends on how your repair estimate compares to the deductible that applies. If gutters are the only damage and the estimate is below a percentage-based hurricane deductible, a claim may not pay. Your agent can walk you through the numbers before you decide.
Will my insurer pay for gutter cleaning after a hurricane?
Routine cleaning is maintenance and is not typically covered. Removing storm debris tied to covered damage may be handled differently under some policies. Ask your insurer how debris removal is treated on your policy.
Can you help me decide whether to file?
We can give you a clear, itemized repair estimate and photos. The decision to file, and any question about coverage, belongs with you, your agent and your insurer.
What if a second hurricane damages my gutters in the same year?
Florida law, in section 627.701 of the Florida Statutes, generally stops insurers from applying the hurricane deductible more than once in a calendar year on personal residential policies. For a later hurricane the same year, the other-perils deductible or what remains of the hurricane deductible typically applies instead. Keep separate photos and records for each storm, and ask your insurer how your policy handles it.
Services mentioned in this guide
Hurricane Gutter Damage Repair
Wind-peeled, bent and detached gutters repaired or replaced after named storms, with photos documenting the damage.
Learn moreFascia Board Repair & Replacement
Rotted fascia cut back to sound wood, new boards primed and finished, and gutters re-hung tight in one visit.
Learn morePost-Storm Debris Clean-Out
Branches, fronds and roof grit cleared from gutters and roof edges after a storm, followed by a photographed damage check.
Learn moreServing Miami-Dade County, Broward County and the rest of South Florida.